
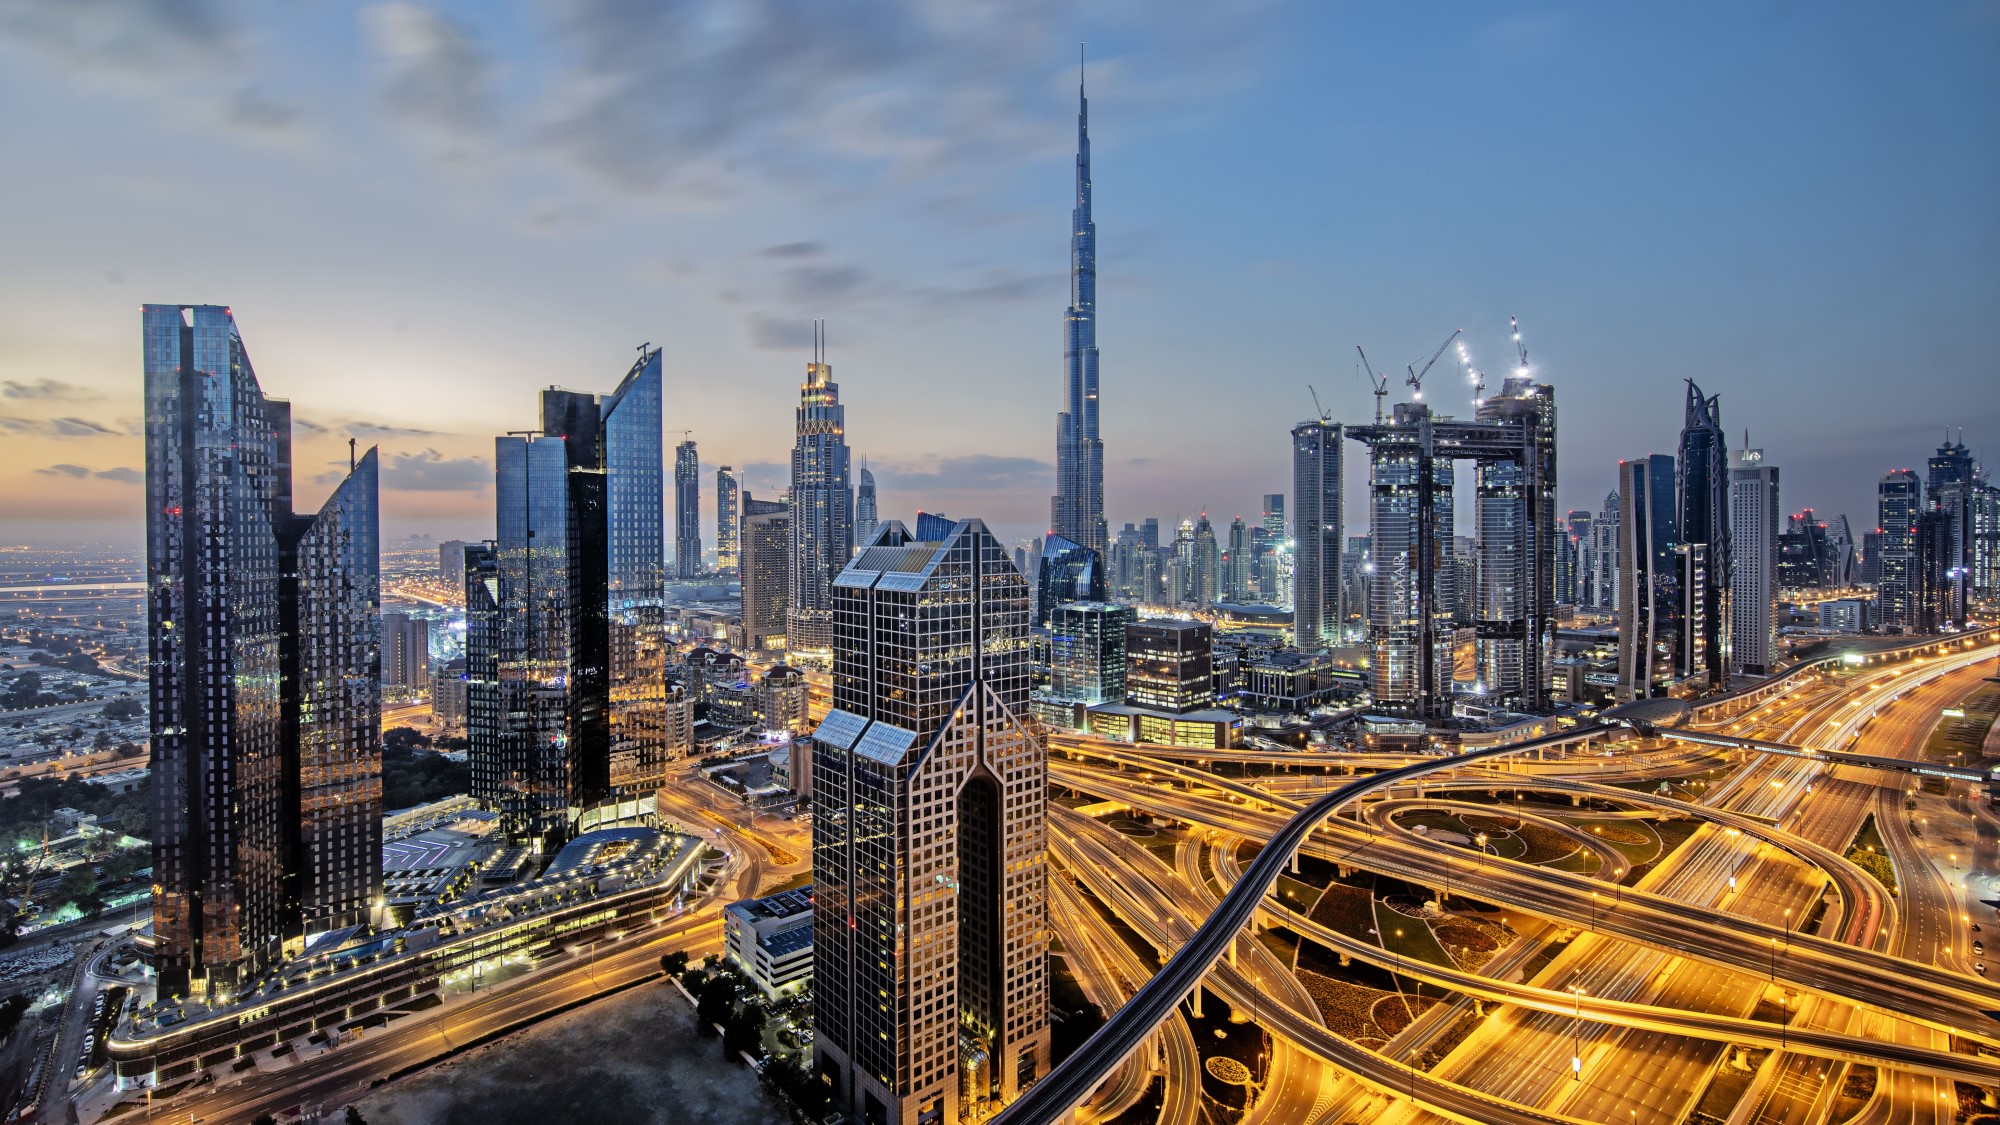
Regional disruption weighed on Dubai’s residential and hospitality markets in Q2 2026, even as offices, retail and industrial held firm, CBRE’s latest UAE review shows
Dubai’s residential market cooled sharply in the second quarter of 2026, and the hospitality sector recorded its steepest downturn in years, according to US-based real estate research firm CBRE’s latest UAE market review. Office and industrial real estate, however, continued to defy a weaker macroeconomic backdrop, the report said.
The figures, published on 28 July, mark a turning point for a residential sector that has driven much of Dubai’s post-pandemic growth story.
Transaction volumes fell 29% year-on-year to just under 37,000 sales in the second quarter, down from more than 51,000 in the same period last year.
Total transaction values dropped even further, to AED88bn ($24bn) from close to AED154bn ($42bn) in the second quarter of 2025.
Rents have moved into negative territory faster than prices. While sales values were still up 1.9% year-on-year, average residential rents fell 2.6% annually and 6.2% quarter-on-quarter.
About 18,000 new units were completed in the first half of the year, adding to supply just as demand and transaction activity were softening.
The contrast with Abu Dhabi is stark. The capital’s residential values rose 21.6% year-on-year, powered by 24.4% growth in apartment prices, while rents climbed a further 3.6%.
Sales values reached AED32bn ($8.7bn), up 150% on the same quarter last year, with transaction volumes up around 80%.
Off-plan sales accounted for roughly 83% of deals and 85% of value, underscoring investor appetite for new launches even as Dubai’s own off-plan pipeline slows.
Hospitality bears the brunt
The hospitality sector recorded the most pronounced downturn of any asset class tracked in the review. Regional geopolitical disruption weighed heavily on international travel demand and airline operations through the first half of the year, with UAE-wide hotel occupancy down 27.7 percentage points year-on-year to June and revenue per available room (RevPAR) down 31.8%, according to CoStar data cited in the report.
Dubai absorbed the sharpest declines, reflecting its greater reliance on international visitor flows, while Abu Dhabi held up comparatively better on the strength of domestic demand and events-led tourism.
Operators have responded with staycation packages, domestic tourism campaigns and refurbishment programmes aimed at protecting market positioning ahead of an anticipated recovery in international arrivals.
Office and industrial hold strong
Away from housing and hotels, the picture is markedly different. Dubai office rents rose 13% year-on-year, with prime rents up 16% and occupancy at about 94%, as demand concentrated in DIFC, Tecom and DMCC continues to outpace the delivery of new Grade A stock.
Abu Dhabi’s office market performed even more strongly, with rents up nearly 16% and occupancy at 96%, driven by ADGM-based financial services firms including hedge funds.
With less than 300,000 square metres (sq m) of new office space due between 2026 and 2027, both emirates face a supply squeeze that is likely to sustain rental growth into next year.
Retail occupancy remained resilient at about 98% in Dubai and 95% in Abu Dhabi despite softer tourism flows and shifting consumer spending, with Dubai rents up around 3% year-on-year.
A new wave of retail supply is in the pipeline, led by Al-Khail Avenue in Dubai and the first phase of Saadiyat Grove in Abu Dhabi.
Industrial and logistics stand out
Underpinned by government-led localisation programmes, the UAE industrial exports reached AED262bn ($71bn) in 2025, with Operation300bn and Make it in the Emirates (MIITE) continuing to draw manufacturing and logistics investment.
Abu Dhabi secured AED48.5bn ($13.2bn) in commitments through MIITE alongside new logistics agreements at Kezad. At the same time, Dubai recorded strong rental growth across Dubai Industrial City, Dubai Investments Park and National Industries Park.
CBRE now forecasts a marginal UAE GDP contraction of 0.04% for 2026, reflecting disruption to trade, tourism and aviation, though it expects a strong rebound in 2027 as regional conditions normalise.
 READ THE JULY 2026 MEED BUSINESS REVIEW – click here to view PDF
Stress test for Gulf aviation; Mixed performance as country outlooks diverge in the Levant; GCC tourism sector pivots from crisis to recovery mode.
Distributed to senior decision-makers in the region and around the world, the July 2026 edition of MEED Business Review includes:
> AIRPORTS: Dubai and Riyadh reaffirm airport ambitions > INDUSTRY REPORT: Dubai eyes tourism sector recovery > DATA CENTRES: Big Tech falls short on data centre promise > LEADERSHIP: Aramco’s citizen developers accelerate digital change |
To see previous issues of MEED Business Review, please click here
You might also like...
Improving capital project delivery: What really works and why
16 September 2026
Engineering progresses on Ras Laffan LNG terminal berths
16 September 2026
Medina’s KEC signs real estate development deal
16 September 2026
Egypt signs agreement for $2bn tyre complex
16 September 2026
A MEED Subscription...
Subscribe or upgrade your current MEED.com package to support your strategic planning with the MENA region’s best source of business information. Proceed to our online shop below to find out more about the features in each package.
Take advantage of our introductory offers below for new subscribers and purchase your access today! If you are an existing client, please reach out to your account manager.